
California treats capital gains differently than the federal government, and that surprise can make a profitable sale feel less profitable at tax time. In most cases, the california capital gains tax is not a separate discounted rate; gains are generally taxed as ordinary income on your California return. This guide explains how capital gains in CA work, what happens with real estate, and the planning steps that can help you avoid an unpleasant bill.
How does California tax capital gains?
California taxes capital gains as ordinary income rather than applying a lower state-level capital gains rate. The Franchise Tax Board says California “does not have a lower rate for capital gains” and that all capital gains are taxed as ordinary income, which is the key difference between federal and California treatment. (ftb.ca.gov)
That means your California tax result depends on your taxable income, filing status, deductions, credits, residency status, and the character of the asset. For many taxpayers, the ca capital gains tax is simply part of the broader California income tax calculation. If a stock sale, business sale, crypto sale, or property sale increases your income, it can also push more of your income into higher California brackets.
For tax year 2026 planning, California’s published rate schedules show progressive personal income tax rates that run from 1% to 12.3%, depending on taxable income and filing status. California also applies a 1% Behavioral Health Services Tax on taxable income above $1,000,000. (ftb.ca.gov)
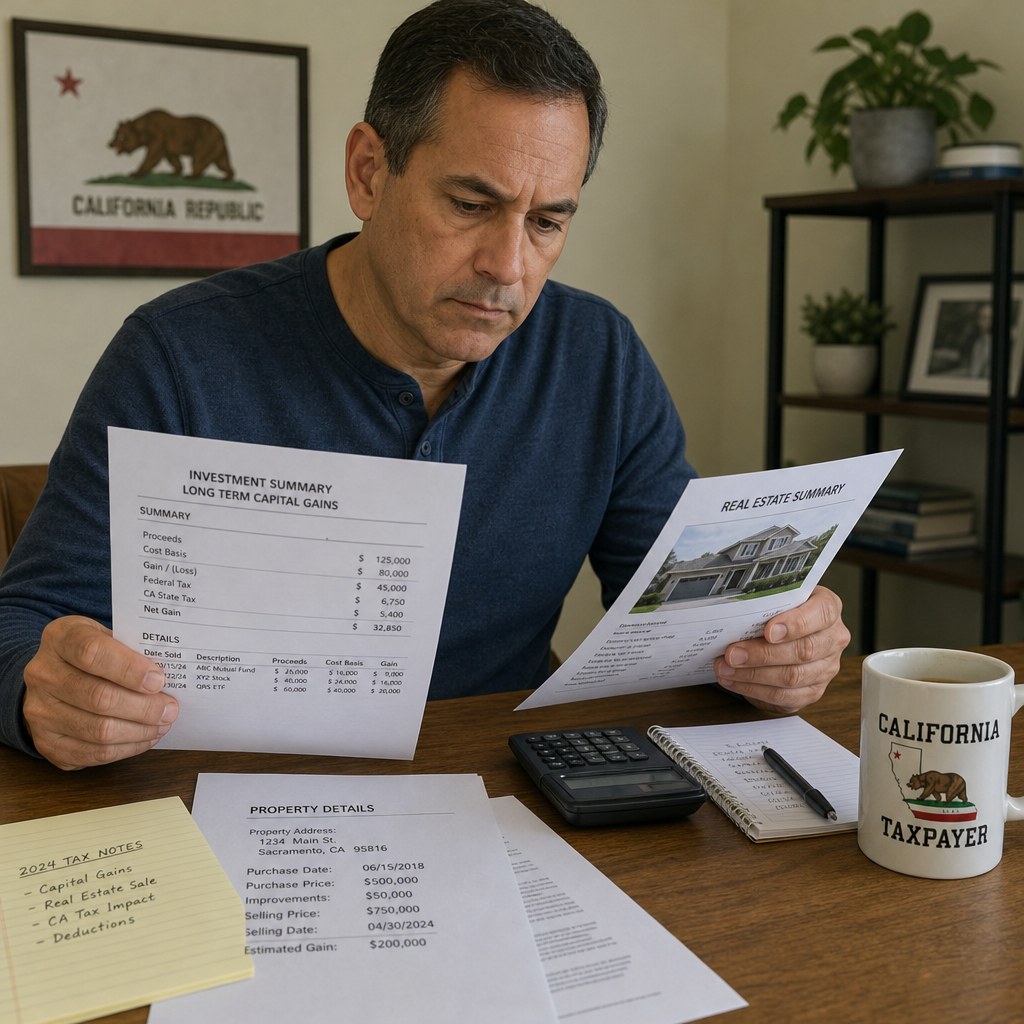
California long-term and short-term gains are treated the same by the state
At the federal level, holding period matters a lot. Long-term gains, usually from assets held more than one year, may qualify for preferential federal rates, while short-term gains are generally taxed like ordinary income. The IRS notes that net short-term capital gains are taxed at ordinary income rates, while most net capital gain is taxed at rates no higher than 15% for many individuals. (irs.gov)
California does not mirror that federal discount. The california long term capital gains tax is still based on ordinary California income tax rules. Likewise, the california short term capital gains tax is also taxed as ordinary income. The practical result is simple: holding an asset for more than one year may help on your federal return, but it does not create a special lower California state capital gains tax rate.
That does not mean holding period is irrelevant. A longer holding period may still improve your federal tax result, affect investment decisions, and give you more time to plan estimated payments, charitable giving, loss harvesting, or sale timing. It just should not be mistaken for a California-specific rate break.
Common assets that can create California capital gains
California capital gains can come from almost any capital asset sold for more than its adjusted basis. Your basis is generally what you paid, adjusted for items such as commissions, improvements, depreciation, or other tax-specific adjustments.
Common sources include:
- Stocks, ETFs, mutual funds, and bonds: Brokerage sales often flow to federal Form 1099-B and federal Schedule D, then into your California return.
- Real estate: A home, rental property, land, or commercial building may create a large gain because appreciation and depreciation can both matter.
- Cryptocurrency and digital assets: Selling, exchanging, or spending crypto can create taxable gain or loss.
- Business interests: Selling partnership interests, S corporation stock, or other business assets may require additional California adjustments.
- Collectibles and personal property: Art, coins, jewelry, vehicles, or other assets can create gains, although personal losses are often limited.
California Schedule D is generally used when California and federal capital gains or losses differ. The FTB instructions state that California Schedule D (540) is used only if there is a difference between California and federal capital gains and losses. (ftb.ca.gov)
California capital gains tax on real estate deserves extra attention
The california capital gains tax on real estate can be one of the most important state tax issues for homeowners, landlords, and out-of-state sellers. California real estate gains can be taxable to California even when the seller no longer lives in the state, because real property is generally sourced to where the property is located. The FTB lists the sale or transfer of California real property as a California-source item for nonresidents and part-year residents. (ftb.ca.gov)
Primary residences may qualify for a federal home sale exclusion. The IRS states that eligible taxpayers may exclude up to $250,000 of gain from the sale of a main home, or up to $500,000 for certain married couples filing jointly. (irs.gov) California generally starts from federal income concepts, but your facts still matter, especially if there were periods of rental use, depreciation, divorce, partial ownership, or a prior exclusion claim. For a home-specific walkthrough, see capital gains tax on a home sale in California.
Real estate sales can also involve withholding. California real estate withholding is a prepayment of tax due from selling California real property, and FTB guidance describes withholding rules that may apply through escrow. (ftb.ca.gov) FTB Publication 1016 explains that withholding can equal 3 1/3% of the sale price or an alternative withholding amount certified by the seller. (ftb.ca.gov)
Residency can change the California tax result
Residency is often where capital gains in CA become complicated. A full-year California resident is generally taxed by California on all income, regardless of where the income comes from. The FTB’s nonresident guidance explains that California taxes residents on all income regardless of source, while nonresidents and part-year residents focus on California-source income. (ftb.ca.gov)
For intangible assets such as publicly traded stock, residency at the time of sale can be especially important. For California real estate, the property location is usually the anchor. Moving out of California before selling a stock portfolio may produce a different state result than moving out before selling California land or a California rental property.
If you are changing residency, keep careful records. California may look at facts such as where you live, work, vote, register vehicles, maintain professional relationships, and spend time. A large gain after a move is the kind of event that deserves documentation rather than assumptions.
A practical checklist before selling an appreciated asset
Before you sell, slow down and estimate the tax impact. A few hours of planning can be worth far more than trying to fix the outcome after the transaction closes. Our seller net proceeds calculator can help you estimate what you may keep before taxes.
Use this checklist:
- Estimate your gain. Start with expected sale proceeds, then subtract adjusted basis and selling costs.
- Separate federal and California treatment. Federal long-term rates may differ from California’s ordinary income approach.
- Review state residency. Confirm whether you are a resident, part-year resident, or nonresident for the sale year.
- Check for California adjustments. Depreciation, basis differences, qualified opportunity fund treatment, or other items may differ from federal law.
- Plan for estimated taxes. A large sale may require quarterly estimated payments or increased withholding.
- Look for offsetting losses. Capital losses may offset gains, but timing and carryover rules matter.
- Consider professional help. Real estate, business sales, stock compensation, and residency moves are rarely do-it-yourself situations.
Federal and California reporting do not always match
Your federal return and California return are connected, but they are not identical. California does not always conform to every federal rule, and the FTB instructions point taxpayers to California adjustments when federal and state treatment differs. (ftb.ca.gov)
For example, the FTB’s Schedule D instructions note that California does not conform to certain federal qualified small business stock exclusions and qualified opportunity zone gain deferrals. (ftb.ca.gov) That can create a situation where a transaction looks partially sheltered on the federal return but taxable for California purposes.
This is why tax software questions matter. If you simply import federal data and skip the California adjustment interview, you may miss a required addition, subtraction, basis change, or carryover detail. The larger the gain, the more important it is to review the state forms before filing.
Smart planning moves for California taxpayers
There is no universal way to eliminate california capital gains tax, but there are practical ways to manage the impact. The right strategy depends on the asset, your income, your timeline, and whether you need cash from the sale. If the property was inherited or transferred in the family, also read selling inherited property in California and Prop 19.
Consider these planning ideas:
- Time the sale thoughtfully. Selling in a lower-income year may reduce the California marginal rate that applies to the gain.
- Harvest losses carefully. Selling losing investments can offset gains, but watch wash-sale rules and portfolio risk.
- Use charitable giving strategically. Donating appreciated assets may be more efficient than selling first and donating cash, depending on your facts.
- Track basis from day one. Improvements, reinvested dividends, depreciation, and transaction costs can change the taxable gain.
- Model the combined tax bill. Look at federal tax, California tax, net investment income tax, withholding, and estimated payments together.
The key is to plan before the gain is locked in. Once the sale closes, your options narrow. Selling costs also reduce your gain, so review seller closing costs in California and the post on real estate attorney closing costs.
The main takeaway
California capital gains are not taxed under a special discounted state system. The california state capital gains tax generally follows ordinary income tax treatment, which means a profitable sale can meaningfully increase your California tax bill. Before selling real estate, investments, crypto, or a business interest, estimate both federal and California results, check for state-specific adjustments, and get qualified tax advice when the numbers are significant.
Selling a California Home?
Know what your home may be worth before you plan around taxes. Get a free home valuation, then talk to a CPA or tax professional about your situation. See how Sell For Mor works.
Free. No obligation to sell.
Keep reading: home selling timeline and essential checklist for selling a house.
This article is general information, not tax or legal advice. Sell For Mor does not provide tax advice; consult a CPA or tax attorney about your situation. Sell For Mor is powered by Rise Realty, DRE #01957687.