
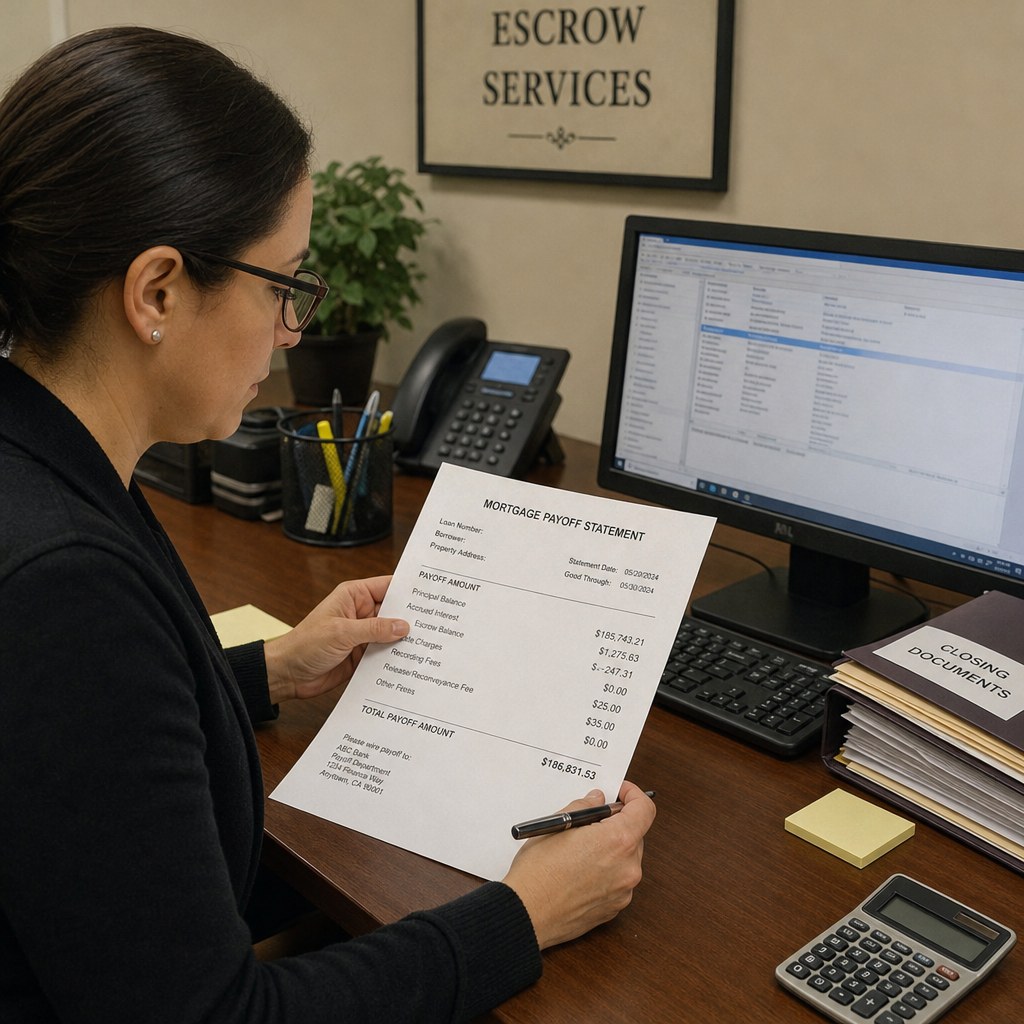
A payoff statement is the written figure escrow uses to pay off a seller’s mortgage at closing. In California, it is often called a mortgage payoff statement, loan payoff statement, or payoff demand, and it shows the amount needed to satisfy the loan as of a specific date. This matters because the balance on a regular mortgage statement is not usually the same amount required to fully release the lien from the property.
This article explains the payoff statement meaning in plain English, how sellers or escrow order one, what the numbers include, and how it fits into a California closing. It is for general information only and does not provide legal advice.
What is a payoff statement?
A payoff statement is a lender or servicer’s written statement showing the total amount required to pay a mortgage or other property-secured loan in full by a stated date. If you are wondering what a payoff statement is for mortgage purposes, think of it as the official final invoice for the loan, not just a snapshot of the current principal balance.
In a California sale, escrow typically needs a payoff demand for every loan recorded against the property. That may include a first mortgage, second mortgage, home equity loan, or home equity line of credit. The payoff amount is then used to calculate how much of the seller’s proceeds must go to the lender before the seller receives any remaining funds. For the escrow process around it, read what is escrow in real estate.
A federal mortgage servicing rule generally requires a creditor, assignee, or servicer to provide an accurate payoff statement within a reasonable time, and no more than seven business days after receiving a written request from the consumer or someone acting on the consumer’s behalf, with limited exceptions. (consumerfinance.gov)
A payoff statement is not the same as your monthly statement
A common seller mistake is assuming the current balance on a monthly mortgage statement is the payoff amount. It usually is not. Your regular mortgage statement is designed for monthly billing. A mortgage payoff statement is designed to close out the entire obligation.
The difference can come from several items:
- Principal balance: The unpaid loan amount before final interest and charges are added.
- Per diem interest: Daily interest that accrues from the statement date through the payoff’s good-through date.
- Unpaid fees or charges: Late fees, recording-related charges, statement fees, or other amounts allowed under the loan terms.
- Escrow balance: Money held for taxes or insurance may be handled separately, credited, or refunded after payoff depending on the servicer’s procedures.
- Reconveyance or release fees: Charges connected with removing the lender’s lien from title after the debt is paid.
That is why the answer to what a house loan payoff statement is more specific than the amount I still owe. It is the amount required to fully satisfy the loan and allow the lien release process to move forward. See selling a house with a mortgage.
The good-through date controls the payoff amount
Every payoff demand has a date through which the stated amount is valid. This is often called the good-through date. The payoff figure includes interest through that date, so escrow must send funds in time for the lender to receive and apply them within the valid period.
If the payoff is not completed by the good-through date, the statement becomes stale. Escrow may need an updated demand, and the seller’s net proceeds can change because additional per diem interest may be added. In a busy closing, even a small delay can require recalculation.
For example, if a payoff is good through the 20th but the closing moves to the 23rd, the original demand may no longer be enough. Escrow will usually request an updated payoff or add the required daily interest if the lender’s instructions allow it. Sellers should avoid relying on an old loan payoff statement from a prior refinance, canceled sale, or earlier estimate.
How sellers and escrow order the payoff demand
In many California transactions, escrow orders the payoff statement directly from the mortgage servicer after the seller signs authorization. The lender normally will not release loan information to escrow, an agent, or another third party without written permission from the borrower.
The process often looks like this:
- Escrow opens the file. After the purchase agreement is accepted, escrow collects seller information and loan details.
- The seller signs written authorization. This allows escrow to contact the servicer and request the payoff demand.
- Escrow submits the request. The request usually includes the borrower’s name, loan number, property address, estimated closing date, and escrow contact details.
- The servicer prepares the payoff. Federal rules generally require a response within seven business days after a proper written request, though practical timing can vary and special loan situations may take longer. (consumerfinance.gov)
- Escrow reviews the demand. Escrow checks the amount, good-through date, wiring or payment instructions, and any special requirements.
Although many payoffs arrive sooner, sellers should not wait until the last minute. If a servicer needs additional authorization, the loan was recently transferred, or the property has more than one lien, delays can affect the closing timeline.
How escrow uses the payoff statement at closing
Escrow uses the payoff demand as a closing instruction for the seller’s mortgage debt. The payoff amount is entered on the estimated settlement statement and final closing statement, reducing the seller’s proceeds from the sale. Our guide to the closing disclosure and seller closing statement shows where it appears.
When the buyer’s funds and loan proceeds are received, escrow disburses money according to the closing instructions. The mortgage payoff is sent to the servicer, commonly by wire or another approved method, and escrow keeps records showing the disbursement. The goal is to ensure the old loan is paid so title can transfer without that lien remaining as an unpaid obligation.
This is one reason payoff accuracy matters so much. If the demand is too low, the loan may not be fully satisfied. If the amount changes because of an unpaid last payment, a stale good-through date, or added fees, escrow has to resolve the difference before or after closing depending on the circumstances. Use the seller net proceeds calculator to estimate how the payoff affects what you keep.
Second mortgages and HELOCs need their own payoff statements
A first mortgage is not always the only loan attached to a California property. Sellers may also have a second mortgage, home equity loan, or HELOC. Each recorded lien generally needs its own payoff demand.
HELOCs require special attention because they are revolving lines of credit. Even if the balance looks low or zero, escrow may need a formal demand and instructions to freeze or close the line so no additional draws occur before closing. A HELOC with an available credit line can create title issues if it is not properly closed and released.
Sellers should disclose all property-secured loans early, including older equity lines they no longer use. If escrow discovers a second lien late in the process, the closing may be delayed while authorization, payoff figures, and release instructions are obtained. See selling a house with a lien in California.
Reconveyance clears the paid-off loan from title
In California, many home loans are secured by a deed of trust. After the mortgage is paid in full, the lien must be released through a process commonly called reconveyance. In simple terms, reconveyance is the recorded release showing that the lender’s security interest in the property has been satisfied.
This step affects title because paying the loan and clearing the public record are related but not identical. The payoff sends money to the servicer. The reconveyance removes the old deed of trust from the property records so it no longer appears as an active lien.
The payoff statement may include a reconveyance fee or recording-related charge. Sellers often notice this fee and wonder why it is separate from principal and interest. It exists because the post-payoff release process involves preparing and recording documentation, not merely accepting the final loan payment.
Want to know what you could net after your payoff?
Get a free home value estimate and see likely proceeds after your mortgage payoff and closing costs. No obligation.
Free. No obligation to sell.
Common payoff statement mistakes to avoid
Most payoff issues are preventable if sellers treat the payoff demand as a time-sensitive closing document. A few practical habits can reduce stress near the finish line.
Watch for stale payoff demands
Do not assume an old payoff statement is still usable. The good-through date matters because interest continues to accrue. If the closing date changes, ask escrow whether an updated payoff is needed.
Coordinate the last mortgage payment
A scheduled automatic payment or unpaid last payment can change the final payoff. If the seller makes a regular payment while escrow is also working from a payoff demand, the servicer may need time to post it. Sellers should ask escrow how to handle any payment due near closing rather than guessing.
Protect wire instructions
Wire instructions fraud is a serious risk in real estate closings. Sellers should not rely on emailed instructions that appear suddenly or differ from earlier instructions. Before sending funds or approving any payoff-related wire change, verify instructions through a trusted phone number already known to be legitimate, not a number supplied in a suspicious message.
Identify every lien early
A forgotten HELOC, old second mortgage, or private lien can delay closing. Review your records and tell escrow about every loan that may be tied to the property, even if you believe the balance is zero.
Key takeaways for California sellers
A payoff statement is the official closing payoff figure for a mortgage or property-secured loan. It differs from a monthly statement because it includes daily interest through a good-through date, possible fees, escrow handling, and release-related charges.
For sellers, the most important steps are simple:
- Sign escrow’s written authorization promptly.
- Provide accurate loan numbers and servicer information.
- Tell escrow about second mortgages and HELOCs.
- Track the good-through date if closing is delayed.
- Verify wire instructions carefully.
- Ask escrow before making a final regular payment near closing.
A clear payoff demand helps escrow pay the correct lender, calculate the seller’s net proceeds, and support the reconveyance process after closing. When the payoff is current and complete, one of the most important parts of the sale can move forward with fewer surprises.
Keep reading: What is escrow · What is a closing disclosure · Selling a house with a mortgage · How selling with Sell For Mor works
This article is general information, not legal advice. Payoff procedures vary by servicer and escrow company. Sell For Mor is powered by Rise Realty, DRE #01957687.